Personal and Commercial Banking: How the Right Bank Helps You Manage Money, Access Capital, and Grow
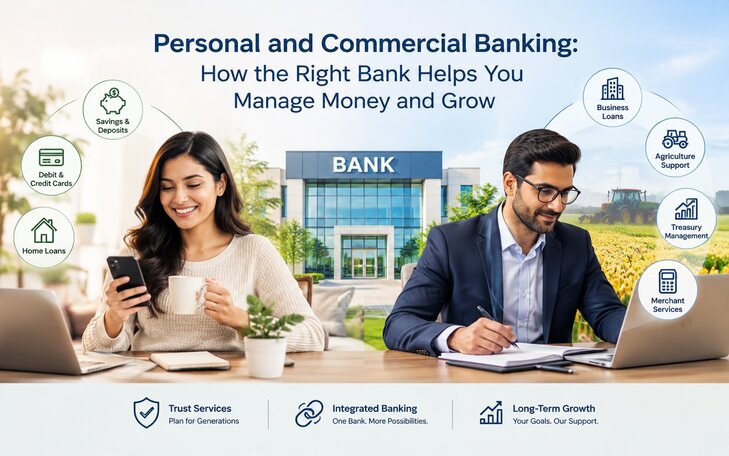
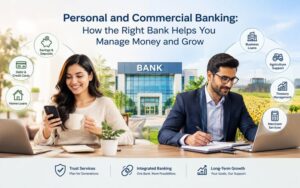
Whether you are opening your first checking account, financing a farm, or scaling a growing company, the bank you choose shapes how easily you can manage money and reach your goals. Among the banks in twin falls idaho, Farmers Bank is a good example of an institution that combines personal and commercial services under one roof. It offers checking and savings accounts, agricultural and mortgage loans, digital banking, commercial lending, treasury management, merchant services, and trust services. That range helps individuals, farmers, and business owners manage their finances, access capital, and operate efficiently with secure, reliable support.
Understanding Personal Banking
Personal banking covers the everyday financial tools people rely on to earn, spend, save, and borrow. At its core are checking and savings accounts. A checking account handles daily transactions such as paying bills, receiving direct deposits, and making purchases. A savings account is where money is set aside for emergencies, major purchases, or long-term goals.
Beyond deposit accounts, personal banking includes lending products such as mortgages, home improvement loans, auto loans, and personal loans. For most households, a mortgage is the largest financial commitment they will ever make, so working with a lender who explains the terms clearly and stays accessible through the process matters a great deal. Community banks like Farmers Bank tend to stand out here because loan decisions are often made locally, by people who understand the regional housing market and the borrower’s circumstances.
Digital banking has also become a basic expectation. Online and mobile platforms let customers check balances, transfer funds, deposit checks, and pay bills at any hour. The best digital tools pair convenience with strong security, including encryption, multi-factor authentication, and real-time alerts that flag unusual activity.
The Role of Commercial Banking
Commercial banking serves a different but connected purpose. It supports the financial needs of businesses, from sole proprietors and small shops to established companies with complex operations. Where personal banking focuses on household stability, commercial banking focuses on liquidity, growth, and operational efficiency.
The centerpiece of commercial banking is lending. Businesses borrow to buy equipment, purchase real estate, fund expansion, manage seasonal cash flow, or bridge the gap between paying suppliers and collecting from customers. A reliable business lender does more than approve or decline an application. It looks at how the business earns money, what its growth plans are, and which loan structure fits. A poorly matched loan can strain cash flow, while a well-structured one can open the door to expansion.
Supporting Agriculture
Agriculture has financial demands that generic banking products often fail to meet. Farmers and ranchers face long production cycles, weather-dependent income, fluctuating commodity prices, and heavy capital needs for land, machinery, livestock, and inputs. Revenue may arrive once or twice a year, while expenses run continuously.
Agricultural loans are built for this reality. They may finance operating costs through the growing season, equipment purchases, land acquisition, or livestock, with repayment schedules tied to the harvest or production calendar. A bank with real agricultural expertise understands these rhythms and can structure credit accordingly, which is why farm-focused lending is a defining strength of community banks in rural and semi-rural regions.
Treasury Management and Merchant Services
As a business grows, its financial operations become more complicated. Treasury management services address this by giving companies tools to control cash flow, streamline payments, and reduce administrative burden. These may include:
- Cash management: monitoring balances and moving funds efficiently across accounts.
- Payment processing: handling ACH transfers, wire transfers, and payroll.
- Fraud protection: safeguards such as positive pay and account monitoring to reduce the risk of unauthorized transactions.
- Reconciliation and reporting: simplifying bookkeeping and improving financial visibility.
Merchant services complement these tools by helping businesses accept card and electronic payments from customers. For retailers, restaurants, and service providers, fast and dependable payment processing directly affects sales and customer satisfaction. Having merchant services and business accounts at the same institution can also simplify deposits, reporting, and problem resolution.
Planning for the Long Term with Trust Services
Some financial needs extend beyond day-to-day banking. Trust services help individuals and families plan for the future by managing assets, supporting estate planning, and carrying out a person’s wishes for how their wealth is held and distributed. For farm and business owners, trust services can play a particularly important role in succession planning, helping ensure that a family operation or company passes smoothly to the next generation.
Access to trust services within the same institution that handles your accounts and loans gives you a fuller picture of your finances. Your banker already understands your assets, obligations, and goals, which makes long-range planning more coordinated.
Why an Integrated Approach Matters
Individuals and business owners often find that their personal and professional finances overlap. A farmer’s household budget depends on the farm’s income. A small business owner may use a personal mortgage or savings to support the company. Working with one bank that serves both sides can reduce friction, improve communication, and give your banker a more complete view of your financial position.
An integrated approach also builds relationships over time. Banks that know their customers can respond more quickly, offer more flexible solutions, and provide better guidance as needs change, whether that means refinancing a home, expanding a business, or planning an estate.
What to Look for in a Bank
When comparing banks, consider these questions:
- Breadth of services: Can the bank meet both your current and future needs, from everyday accounts to commercial credit and trust services?
- Local knowledge: Does it understand your industry and community, especially if you work in agriculture or run a small business?
- Digital capabilities: Are online and mobile tools secure, intuitive, and full-featured?
- Accessibility: Will you be able to reach a real person who knows your situation?
- Stability and security: Does the bank prioritize the protection of your funds and data?
Final Thoughts
Personal and commercial banking are two sides of the same goal: helping people and businesses use money effectively. Checking and savings accounts create everyday stability, loans open doors to homes, farms, and expansion, and treasury, merchant, and trust services keep operations running smoothly and protect what has been built. Institutions like Farmers Bank show how a full-service bank, backed by secure and reliable support, can act as a long-term financial partner for individuals, farmers, and businesses alike. By choosing a bank that fits your goals and understands your world, you put yourself in a stronger position to manage today’s finances and plan for tomorrow.
Pranab Bhandari is an Editor of the Financial Blog “Financebuzz”. Apart from writing informative financial articles for his blog, he is a regular contributor to many national and international publications namely Tweak Your Biz, Growth Rocks ETC.